Afraid of a Mortgage? How Gen Z Buyers in St. Louis Can Move Forward With Confidence
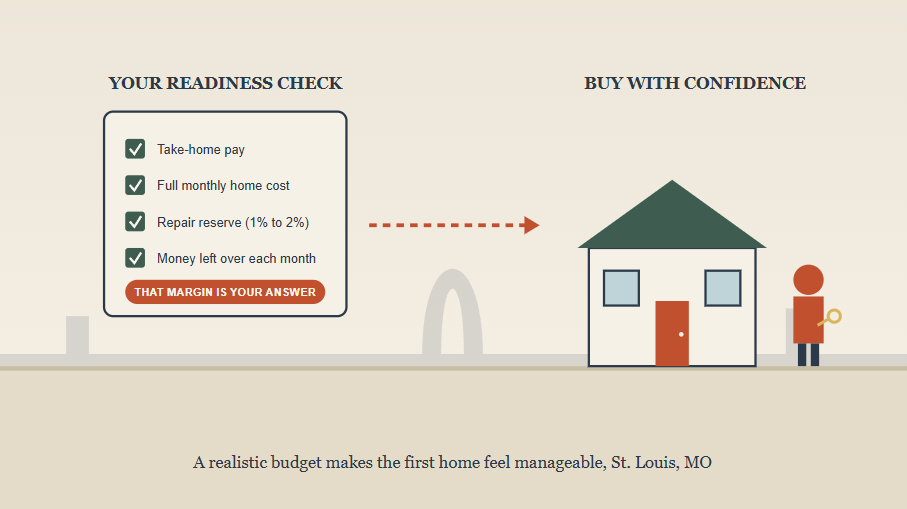
Buying a first home in St. Louis feels less overwhelming with a realistic budget and a lender you trust.
If you rent in St. Louis and keep telling yourself you’ll look at homes “someday,” you’re in good company. Plenty of young adults have saved, kept their credit clean, and still feel stuck at the starting line. The hesitation usually has less to do with money than with confusion and trust. Here is a practical way to cut through both.
Start With Your Monthly Margin, Not Your Pre-Approval
A pre-approval tells you what a lender is willing to lend. It doesn’t tell you what feels comfortable. Before you browse a single listing, run this five-minute check:
- Take-home pay: Use what actually lands in your bank account each month, not your gross salary.
- Total cost of one specific home: Add principal, interest, property taxes, homeowners insurance, mortgage insurance if it applies, and any HOA dues.
- Repair reserve: Set aside roughly 1% to 2% of the home’s price per year for maintenance.
- Your everyday life: Subtract debt payments, groceries, utilities, savings contributions, and spending money.
What remains is your margin. If an unexpected $1,500 furnace repair would land on a credit card because there’s nothing left, that home is too much, even if a lender would approve it. If the margin feels healthy, you’re likely closer to ready than you think.
Why Buying Feels So Scary Right Now
A recent FirstHomeIQ and National MI survey of 1,000 Gen Z and millennial consumers shows how common these worries are:
- 63% feel overwhelmed by homebuying information
- 42% have delayed talking to a housing professional
- 37% avoid thinking about buying altogether
- 76% believe buying is harder than it was for their parents
- About 60% fear being taken advantage of, pressured, or kept in the dark
Notice what’s missing: most of these fears are about information and trust, not about a lack of income. That’s good news, because both are fixable.
Three Myths That Keep Renters Waiting
Myth 1: You need 20% down. About half of respondents believed this. In reality, many loan programs allow far less, and the down payment is only one piece of the total picture. Closing costs, cash reserves, and monthly affordability matter just as much.
Myth 2: Rates need to match what your parents or a friend got. Comparing today’s rate to a past one can make buying feel hopeless, and it can tempt you to wait for a number that may not come back soon. Years spent guessing the perfect moment are years of rent payments and missed opportunities. A better question is whether the payment works for your budget today.
Myth 3: You have to buy now or fall behind. Social media makes it look like everyone is moving into a new place. More than half of survey respondents worry about being rushed into choices they don’t understand. Your timeline is yours.
Ways St. Louis Buyers Make the Numbers Work
The survey found that many younger buyers are getting creative:
- 43% would consider a smaller home or a fixer-upper
- 42% would move to a lower-cost area
- 35% would use a down payment assistance program
Locally, that can look like widening your search to a neighboring community, being open to a home that needs cosmetic updates in the kitchen or bathrooms, or asking a lender whether you qualify for a Missouri down payment assistance program.
Questions to Ask Before You Choose a Lender
Trust is the biggest barrier in the research, so interview your lender the way you’d interview any professional. Good questions include:
- Do you charge broker fees or origination fees, and what exactly is in the closing costs?
- Is a lender credit available to offset closing costs?
- How quickly can you close, and who handles my file day to day?
- Can you show me a side-by-side comparison of two or three loan options in plain English?
- What would my payment look like at a few different down payment amounts?
A good lender answers clearly, doesn’t rush you, and welcomes the comparison. Read reviews, ask friends who recently bought, and talk to more than one.
When Waiting Is the Smart Move
Not ready? That’s a legitimate answer. If your margin is thin, your debt is high, or your savings are light, a few months of focused work can put you in a much stronger spot. Paying down balances, building a repair cushion, and growing your income all improve your options later. The goal is a purchase you’ll still feel good about years after closing.
Quick Answers for St. Louis First-Time Buyers
How much do I really need to save to buy a home in St. Louis? There’s no single number. Plan for your down payment, closing costs, and a cash reserve after closing. Many buyers put down less than 20%, and some lenders can offer credits that reduce upfront closing costs.
Should I wait for mortgage rates to drop before buying? Timing rates perfectly is nearly impossible, and waiting has its own cost. Focus on whether the monthly payment fits your margin today, then talk to a lender about your options if rates change later.
Is it better to keep renting or buy a smaller home? It depends on how long you plan to stay and how stable your income is. A smaller or lower-priced home often gives first-time buyers more breathing room in the monthly budget, along with the chance to build equity.
Your Local St. Louis Mortgage Team
Since 2004, Carlson Mortgage loan officers have helped over a thousand St. Louis home buyers find the right loan, including conventional, FHA, VA, and jumbo financing up to $3.5 million. We’re rated the #1 mortgage company on Yelp and top-rated on Zillow, Facebook, and Google.
Call or text: 314-329-7314 Apply securely: www.carlsonstl.com/apply Email: info@carlsonstl.com
Share Your Thoughts!